

Beyond the Metros: India’s next 11 real estate hotspots
A new report by the Confederation of Indian Industry (CII) and Knight Frank India identifies 11 “next” real estate markets that are recording faster residential price growth than the country’s top eight cities

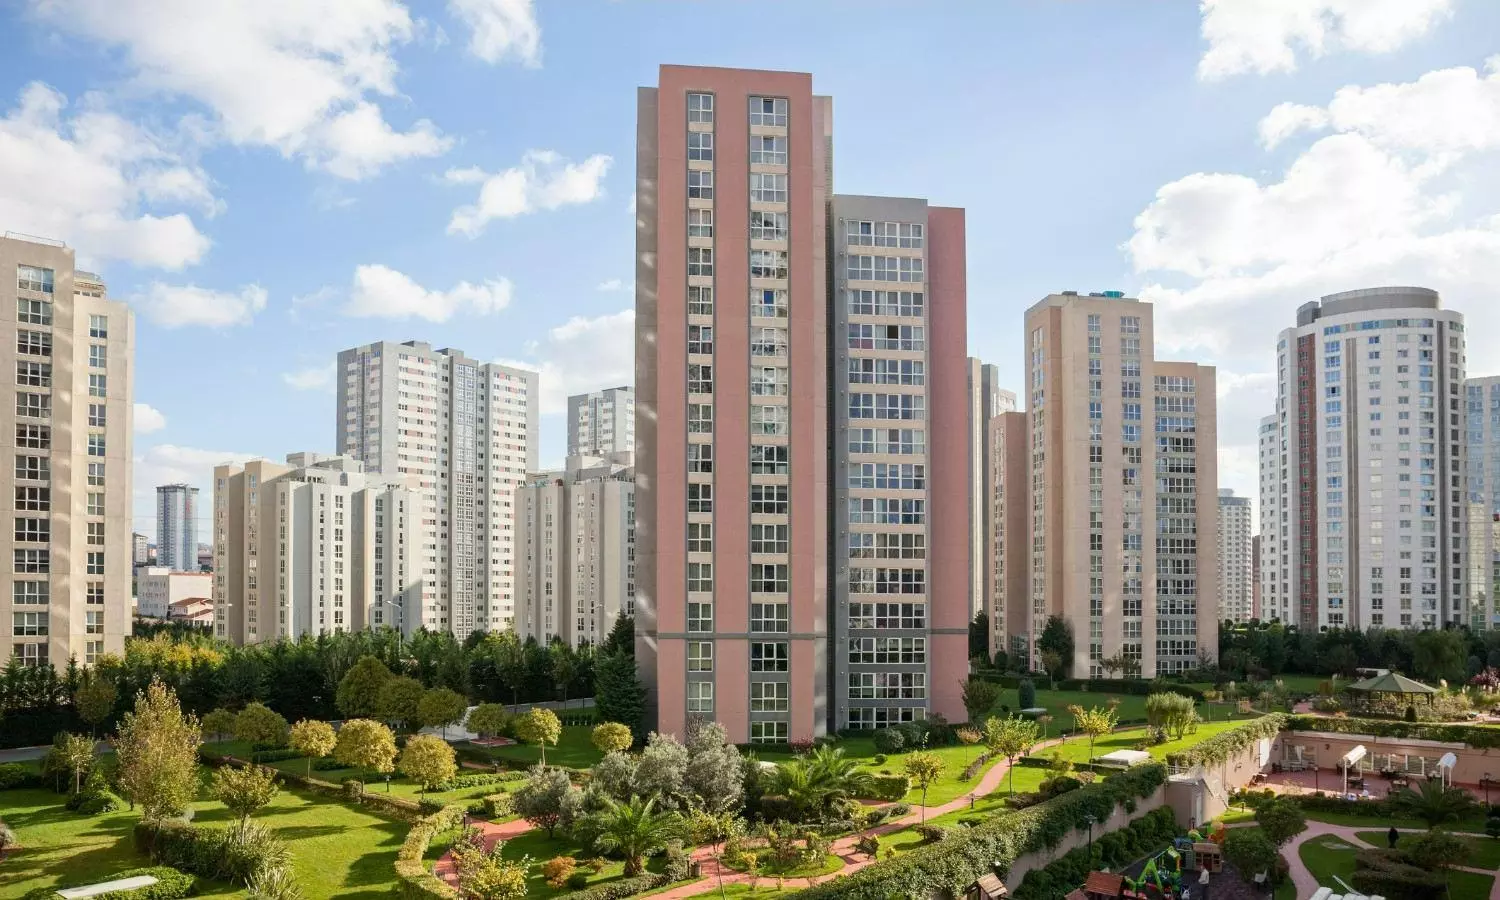
For homebuyers who have watched property prices in Mumbai, Delhi-NCR, Bengaluru and other big cities steadily move out of reach, India’s real estate story may be shifting to a different set of addresses. From Indore and Jaipur to Lucknow, Bhubaneswar and Coimbatore, a clutch of Tier-2 cities is emerging as the next major growth engine for housing, retail and logistics.
A new report by the Confederation of Indian Industry (CII) and Knight Frank India identifies 11 “next” real estate markets that are recording faster residential price growth than the country’s top eight cities. The report says these markets registered an average residential price CAGR of 8 per cent between 2016 and 2026, against 4 per cent across the top eight cities.
More strikingly, the gap has widened in the past five years. Between 2021 and 2026, residential prices across the 11 markets rose 63 per cent, compared with 42 per cent in the top eight cities.
Also read: Indians want bigger homes, but soaring prices impact purchases: Survey
For consumers, however, the bigger story is not simply appreciation. The question is whether these cities can offer something increasingly difficult to find in the metros: relatively accessible housing combined with improving infrastructure, jobs, connectivity, and urban amenities.
Where are the new growth markets?
The 11 cities identified by the report are Bhopal, Bhubaneswar, Chandigarh Tricity, Goa, Indore, Jaipur, Kochi, Lucknow, Nagpur, Visakhapatnam and Coimbatore.
Current average residential prices in these markets range from about Rs 4,500-6,500 per sq ft in Nagpur and Visakhapatnam to Rs 11,500-13,500 per sq ft in Goa. In cities such as Bhopal, Indore, Lucknow and Coimbatore, quoted average price bands remain broadly in the Rs 5,000-9,000 per sq ft range.
That does not necessarily mean homes in these cities are “cheap”. Prices vary significantly by locality, project quality and proximity to employment hubs. But compared with the country's most expensive metropolitan markets, the lower entry price can make home ownership more attainable for many middle-class households.
Also read: Cheaper clothes, smaller cities: How value fashion is reshaping India’s apparel market
For buyers, this also changes the calculation. A city that offers a lower initial property cost but weak employment prospects may not provide the same long-term value as one where infrastructure investment is accompanied by sustained economic activity.
It’s not just about cheaper homes
The report's central argument is that infrastructure is becoming a catalyst for a broader urban transformation.
The share of infrastructure expenditure in total government capital expenditure increased from 39 per cent in FY2015 to 55 per cent in FY2026, according to the report. The government’s three-year public-private partnership pipeline comprises 852 projects with a combined estimated cost of Rs 17 lakh crore.
For consumers, the impact of such spending goes beyond faster travel. Better roads, airports, public transport, utilities and connectivity can influence where companies locate offices, where warehouses are built and where new residential developments come up.
That, in turn, can affect commute times, employment opportunities, rents and eventually property values.
Knight Frank India chairman and managing director Shishir Baijal said the opportunity in Tier-2 and Tier-3 cities would depend not merely on infrastructure creation but on the ability to convert connectivity into sustained economic activity.
Also read: UPI MDR: Centre to ensure merchants don’t charge customers
In other words, a new highway or airport alone may not be enough. The more important question for a prospective homebuyer is: Are jobs, businesses and people following the infrastructure?
Retail and warehouses are following the consumer
There are signs that economic activity is already spreading beyond the metros.
In 2025, key Tier-2 markets recorded 11.2 million sq ft of warehousing lease transactions, broadly similar to the 11.4 million sq ft recorded in 2024. Six of the identified markets — Lucknow, Jaipur, Nagpur, Indore, Coimbatore and Bhubaneswar — accounted for 5.3 million sq ft of those transactions.
For consumers, warehousing growth may sound like an industrial statistic, but its effects can be visible in everyday life. More logistics infrastructure can support faster delivery networks, organised retail and the expansion of consumer businesses into smaller cities.
Retail is expanding too. India had 134 million sq ft of organised shopping-centre stock across 32 cities and 365 shopping centres in 2025. Of this, 36 million sq ft was located across 24 Tier-2 cities.
Ten of the 11 identified markets together accounted for around 60 per cent of Tier-2 shopping-centre stock.
For residents, that translates into a gradual shift in the urban experience — more organised retail, entertainment, dining and consumer services without necessarily having to move to a major Metro.
The population shift could reshape demand
Longer-term demographic projections make the story even more significant.
According to the report, India’s urban population is projected to reach around 740 million by 2050. The number of cities with populations above one million, excluding the top eight cities, is expected to rise from 74 to 85. Cities outside the eight largest metros are projected to record population growth of around 28.2 per cent, compared with 8.7 per cent for the top eight.
For the housing market, population growth matters because new households create demand for homes, schools, hospitals, shops, offices and transport.
The report also points to the expanding role of enterprise. MSMEs contribute around 31 per cent of India's GDP, 35 per cent of manufacturing output and 49 per cent of exports, while Tier-2 and Tier-3 cities account for around half of the country’s more than 200,000 registered startups.
What should homebuyers watch?
The numbers suggest that India's real estate map is becoming more distributed. But buyers should distinguish between price growth and sustainable city growth.
A rising property price does not by itself guarantee that a particular locality will continue appreciating. Buyers would need to examine employment centres, actual infrastructure delivery, social amenities, water and power supply, commuting patterns, land availability and the credibility of developers.
The CII-Knight Frank report estimates that India’s real estate sector could reach an output of USD 5.8 trillion by 2047, with Tier-2 and Tier-3 cities potentially contributing 25-30 per cent of that output.
For India's aspiring homeowners, the significance may ultimately be simpler: the next generation of property markets may not be concentrated around the traditional metro skyline. They could increasingly emerge in city-regions where jobs, infrastructure, consumption and housing demand meet.
For buyers priced out of the biggest cities, that could mean a much wider menu of places to live — and potentially a new way of thinking about where India's next urban centres will be built.