


‘Policyholder, not commissions, must be at heart of IRDAI reforms’: N Rangachary
IRDAI's first chairman weighs in on proposal to slash agents' remuneration, need for cap on expenses, why regulation and development must go hand-in-hand

Come October 23, and it will be exactly 26 years since the first batch of private insurers received registrations from the Insurance Regulatory and Development Authority of India (IRDAI).
But regulatory uncertainty still prevails for about 60 insurers in the life, general, and standalone health sectors. The latest is IRDAI’s proposal to reduce the remuneration paid to intermediaries — agents (individual and corporate) and brokers — which many industry officials are of the view could result in consolidation and further reduce insurance penetration.
Further, IRDAI’s latest proposal may not attract foreign insurance players even though 100 per cent foreign direct investment (FDI) is now allowed. Ironically, 26 years ago, the FDI limit was 26 per cent.
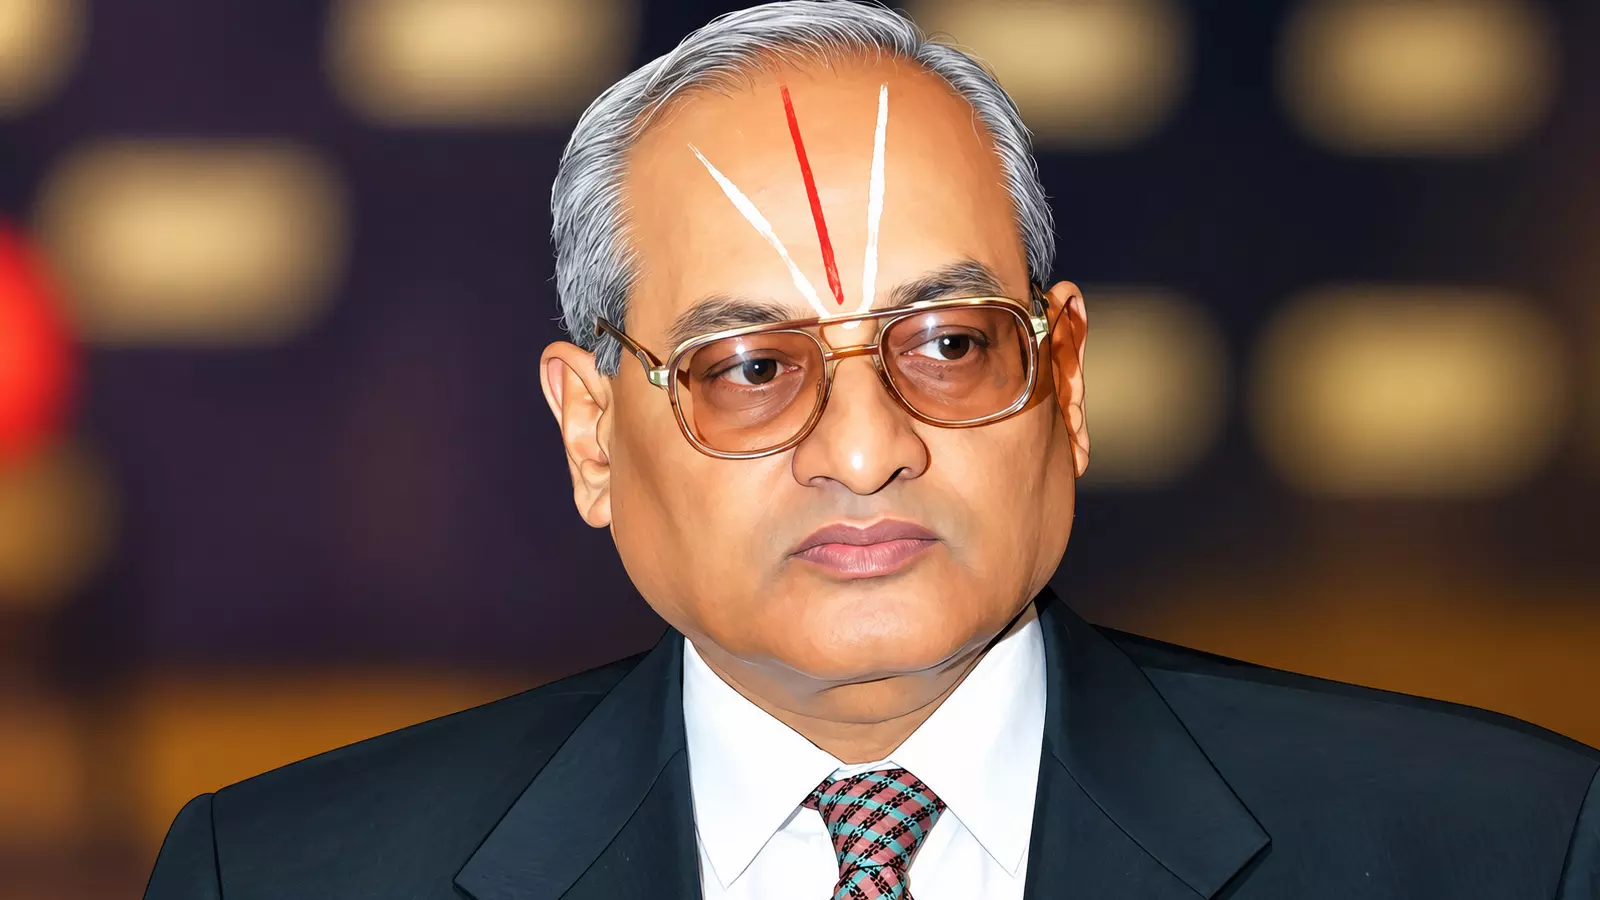
N Rangachary, the first chairman of IRDAI, who had laid the path for the entry of private players, believes the regulator’s proposal to reduce intermediary remuneration may be good for a developed market, but not for India where the insurance penetration is still less than five per cent.
Can India afford to slash intermediary payout?
“At a time when India's insurance penetration remains disappointingly low, the industry requires greater distribution capacity, more professional advice and sustained efforts to develop insurance consciousness among the public. It would be unfortunate if reforms intended to improve affordability inadvertently reduced the availability and quality of these services,” he said in an exclusive interview with The Federal.
The IRDAI should investigate cases where high payouts are being made by insurers to intermediaries and act on them instead of summarily slashing remuneration – Rangachary
Also read: Why are LIC and other insurance agents worried about IRDAI’s proposed overhaul?
The IRDAI should investigate cases where high payouts are being made by insurers to intermediaries and act on them instead of summarily slashing remuneration, Rangachary added.
Why prompted IRDAI proposal?
IRDAI has come out with the latest proposal after seeing the effect of the changes it introduced in 2023. That year, the insurance regulator abolished product-wise commission caps and stipulated an overall limit for Expenses of Management.
According to IRDAI, after the 2023 regulation, the growth in the number of policyholders and premium has not been commensurate with the increase in payouts to intermediaries.
IRDAI hopes its proposed norms would result in lower premiums for policyholders, which Rangachary and others are of the view may not happen.
Why insurers have expense limits
On the logic of having limits on the Expenses of Management (costs that insurers or investment companies incur in running their business) for insurers when no other industry has such a statutory limit, Rangachary said: “Insurance is a long-term business and the fundamental principle on which it runs is that the promise of paying claim will be honoured. For that purpose, the insurer’s solvency should be ensured, as companies cannot be allowed to squander their monies. The sectoral regulator ensures the solvency by stipulating the limits for Expenses of Management and the investment norms.”
Also read: IRDAI insurance reforms: Lower costs may not be enough without better claims
Clarifying that he is not against regulatory reforms, Rangachary said: “Reform must be founded upon sound economic reasoning, empirical evidence, proportionality and a clear understanding of consequences. The insurance regulator must remain uncompromising on solvency, governance, fair market conduct, mis-selling, claims settlement and policyholder protection. Good intentions cannot substitute for good regulatory outcomes."
Where should regulation end?
Rangachary says prescribing detailed commercial remuneration structures across products and distribution channels also raises legitimate questions concerning the appropriate boundaries of regulatory intervention. “Insurers' boards are responsible for business strategies, operating efficiency and commercial decisions, subject to prudential and conduct regulation. Regulatory supervision should not progressively substitute administrative judgment for market competition without compelling justification,” Rangachary said.
A policyholder needs to know whether a policy is suitable, whether exclusions have been properly explained, whether the insurer will honour legitimate claims and whether dependable assistance will be available when needed. These outcomes matter considerably more than an isolated commission percentage, says Rangachary.
“Equally, the regulator must remain accountable for the consequences of its interventions,” Rangachary added.
According to him, Indian insurance policyholders continue to face significant challenges relating to claims repudiations, settlement delays, inadequate disclosures, complicated policy wording, medical inflation and insufficient grievance redressal.
Also read: Insurance mistakes most Indians make: Expert reveals what you need to know
“Mis-selling must be addressed decisively, but responsibility must be determined fairly across insurers, product design and distribution channels. A policyholder needs to know whether a policy is suitable, whether exclusions have been properly explained, whether the insurer will honour legitimate claims and whether dependable assistance will be available when needed. These outcomes matter considerably more than an isolated commission percentage,” Rangachary remarked.
Assess impact before changing the system
According to him, IRDAI should consider commissioning independent economic, actuarial, competition and employment impact assessments, disclosing the assumptions underlying the proposed reforms and evaluating reasonable alternatives.
“Any transition should be gradual, proportionate and demonstrably linked to policyholder welfare. The objective should not be to preserve existing arrangements merely because they have existed for many years. Institutions must evolve, and inefficiencies must be corrected. But equally, an architecture deliberately created to professionalise insurance distribution should not be fundamentally altered without convincing evidence that the proposed replacement will produce superior outcomes,” he said.
IRDAI has a development mandate too
Pointing out the development mandate of IRDAI, Rangachary said: “The insurance regulator must remember that its statutory mandate encompasses both regulation and development of the insurance sector. Development cannot be achieved by weakening the very distribution networks that connect millions of Indians to financial protection.”
Also read: Your PF, insurance savings could help fund India’s next infra boom. Here’s the challenge
“The ultimate measure of regulatory success is not how much commission has been eliminated, but how many more Indians have secured meaningful insurance protection, how fairly and promptly claims are settled, and how effectively the insurance system serves society. The policyholder must remain at the heart of every regulatory reform—not merely in its stated intentions, but in its demonstrable and measurable outcomes,” Rangachary concluded.